The first thing that's important to understand about the Indiana insurance market is that there are two carriers leaving the individual (ACA) market, and one possibly (?) leaving the small group market next year.
In accordance with the provisions of 211 CMR 66.08(3)(e), and in order to ensure that insurance rates are fair to consumers, the Division of Insurance reviews and seeks public comment on the rates requested by health insurance carriers.
The following tables depict the proposed overall weighted average premium increase and the key assumptions behind premium development for the merged (individual and small employer) market filed by insurance carriers as part of the Massachusetts Division of Insurance rate review process (for rates effective in 2027). This information is subject to change as the rate review process continues.
The Health Care Access Bureau within the Massachusetts Division of Insurance is currently reviewing these assumptions. This review process will culminate in a final decision in August 2026.
Merged Market Summary for Proposed Rates Effective for 2027
The past couple of weeks have been pretty brutal for the Oregon health insurance market.
On May 21st, Providence Health Plan announced that they were shutting down pretty much their entire insurance division across Oregon (which also impacts some people in Washington and California):
Providence Health & Services plans to exit most of its Oregon health insurance business next year, citing rising costs, tougher regulation and intensifying competition from national insurers — a move that will force hundreds of thousands of Oregonians to find new coverage.
...Providence Health Plan, based in Portland, is Oregon’s third-largest health insurer, covering more than 421,000 Oregonians. It also covers over 13,000 members in Washington and 4,800 in California.
Mending Health Notifies Maine Bureau of Insurance that it Will Cease Offering Health Insurance Plans
AUGUSTA, ME – Mending Health, formerly known as Taro Health, has notified the Maine Bureau of Insurance that it will no longer offer health insurance as of January 1, 2027.
Mending Health’s approximately 1,100 members will keep their health plans through the end of their existing plan year.
Individuals/families who obtained Mending coverage through CoverME.gov, or who purchased a plan directly from Mending Health, can select a new plan with another health insurance company during the annual open enrollment period beginning November 1, 2026. New coverage will take effect January 1, 2027.
Every year around this time I start my annual individual & small group market rate filing analysis project. This involves spending months painstakingly tracking every insurance carrier rate filing for the upcoming year to determine just how much average insurance policy premiums on the individual market are projected to change.
Carriers tendency to jump in and out of the market, repeatedly revise their requests, and the confusing blizzard of actual filing forms sometimes make it next to impossible to find the specific data I need.
The actual data I need to compile my estimates are actually fairly simple, however. I really only need three pieces of information for each carrier:
ACA exchangeenrollment has only dropped by about 4% in Texas since Congressional Republicans allowed the enhanced federal subsidies to expire at the end of last year.
Initial signups during Open Enrollment were actually up about 5% vs. OEP 2025...but effectuated enrollment quickly dropped to practically even year over year in January and was down 4.3% as of February.
Still, thanks largely to Texas having a robust Premium Alignment policy in place (which they boosted a bit more this year, as I understand it), the drop-off in the Lone Star state has been far more modest than in most of the country. Even so, that's still over 146,000 Texans who lost healthcare coverage in just the first two months of the year.
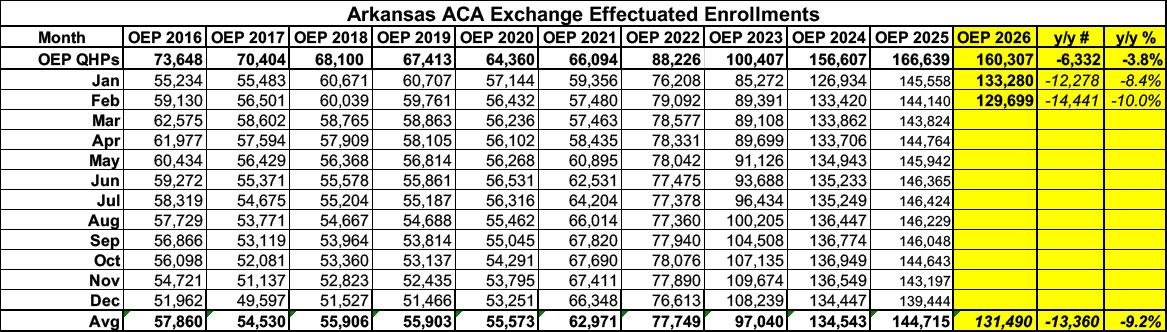
ACA exchange enrollment has dropped by 10% in Arkansas since Congressional Republicans allowed the enhanced federal subsidies to expire at the end of last year.
Initial signups during Open Enrollment were only down 3.8% vs. OEP 2025...but effectuated enrollment was down over 8% year over year in January and by 10% (around 14,000 enrollees) as of February.
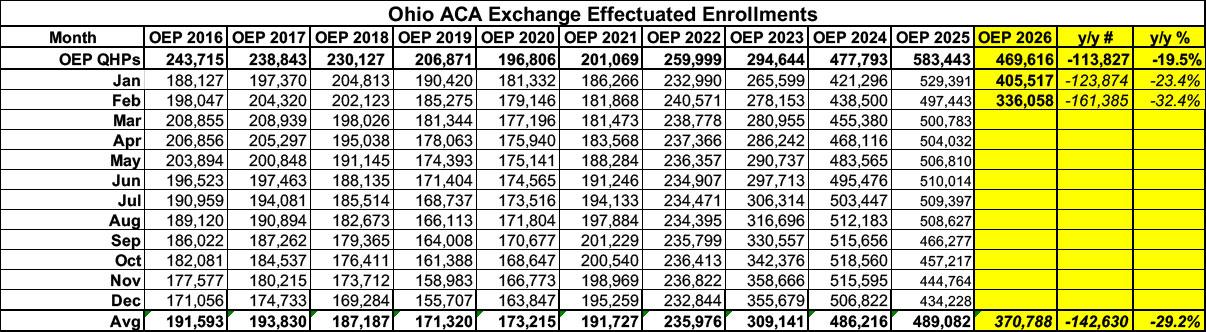
ACA exchange enrollment has dropped by 32% in Ohio since Congressional Republicans allowed the enhanced federal subsidies to expire at the end of last year.
Initial signups during Open Enrollment were down nearly 20% vs. OEP 2025...but effectuated enrollment dropped further, by 23% year over year in January and by over 32% in February.
That's over 160,000 Ohioans who already lost coverage in just the first two months of the year...a number which has likely continued to climb since then.
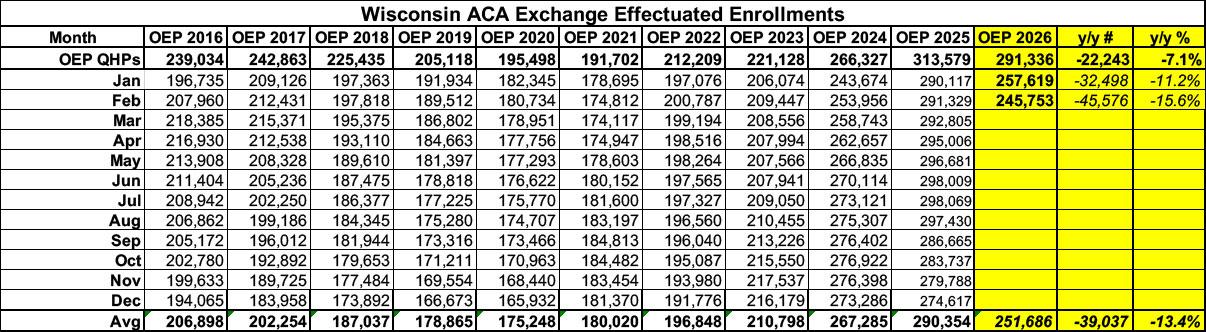
ACA exchange enrollment has dropped by over 15% in Wisconsin since Congressional Republicans allowed the enhanced federal subsidies to expire at the end of last year.
Initial signups during Open Enrollment were down 7% vs. OEP 2025...but effectuated enrollment was 11% lower year over year in January, rising to 15.6% lower as of February.
That's over 45,000 Wisconsinites who already lost coverage in just the first two months of the year...a number which has likely continued to climb since then.
Here's what this looks like visually, with both 2025 and 2019 (the last pre-COVID year, which didn't include the enhanced subsidies) included for comparison:
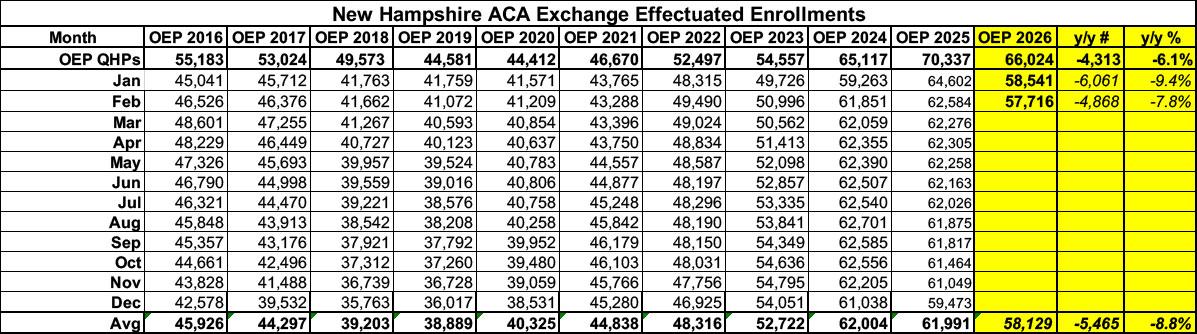
ACA exchangeenrollment has dropped by ~8% in New Hampshire since Congressional Republicans allowed the enhanced federal subsidies to expire at the end of last year.
Initial signups during Open Enrollment were down ~6% vs. OEP 2025...but effectuated enrollment shrank by a bit more in the first two month sof the year...although interestingly it actually nudged back up a smidgen in February relative to a year earlier.
Here's what this looks like visually, with both 2025 and 2019 (the last pre-COVID year, which didn't include the enhanced subsidies) included for comparison: